 By Cailyn Theo
Walk onto any gaming floor in Las Vegas or Atlantic City, and you will see dozens of distinct betting styles. Some visitors rely on superstitious rituals, others stubbornly stick to flat table minimums, and a concerning number chase losses through aggressive doubling systems like the Martingale. While these approaches vary wildly in execution, they share a fundamental flaw: they treat bet sizing as an emotional impulse or an arbitrary habit rather than a mathematical function of risk and reward.
In the world of quantitative finance and professional advantage play, capital allocation is governed by rigorous probability. The most famous framework for this discipline is the Kelly Criterion, a formula developed in the mid-twentieth century to determine the mathematically optimal size of a series of bets. While originally designed for technical telecommunications, the formula became the foundational bankroll management system for legendary gamblers and Wall Street investors alike.
Understanding how the Kelly Criterion works will not give you supernatural luck, but it will fundamentally change how you view your gambling bankroll, your risk exposure, and the true cost of casino games.
What the Kelly Criterion Actually Is
The formula was conceived in 1956 by John L. Kelly Jr., a physicist working at Bell Labs. Kelly was analyzing signal noise over long-distance telephone lines, searching for ways to maximize the transmission of data without overloading the channel. Around the same time, legendary mathematician Edward O. Thorp recognized that Kelly’s data-transmission mathematics solved an age-old gambling conundrum: how much of your total capital should you wager when you hold a verifiable edge?
Thorp used Kelly’s formula to run the first mathematically proven card-counting teams in blackjack, later applying the exact same logic to launch one of the most successful statistical arbitrage hedge funds in financial history.
At its core, the Kelly Criterion answers a specific question: what exact percentage of your bankroll should you wager to achieve the highest possible rate of compounded geometric growth over the long run, while driving the mathematical probability of going completely broke to zero?
Unlike flat betting, where you wager the same fixed dollar amount regardless of bankroll fluctuations, Kelly is a proportional betting strategy. When your bankroll grows, your bets expand proportionally. When your bankroll shrinks, your wagers automatically contract. This dynamic scaling protects capital during severe drawdowns and accelerates compounding during winning stretches.
The Brutal Reality Check for Casual Players
Before applying the formula to a casino visit, casual players must confront an uncomfortable mathematical reality: the Kelly Criterion only works when the bettor has a positive mathematical edge.
In the formula, your edge represents the statistical advantage you hold over the house. If you calculate the Kelly formula on European roulette, craps, baccarat, three-card poker, or slot machines, the math produces a negative number. A negative Kelly result delivers a definitive operational command: do not place a bet. In pure Kelly terms, the only optimal wager on an un-advantaged casino game is zero dollars.
Casinos generate guaranteed corporate profits because every standard table game and gaming machine features a built-in house advantage, typically ranging from 0.5 percent on perfect-strategy blackjack to over ten percent on novelty side bets and slots. Because the house holds the mathematical edge, no staking plan, progression system, or timing strategy can turn a negative-expectation game into a winning one over a large sample of trials.
Where Kelly becomes relevant in a casino environment is in scenarios where an educated player can flip the edge in their favor:
-
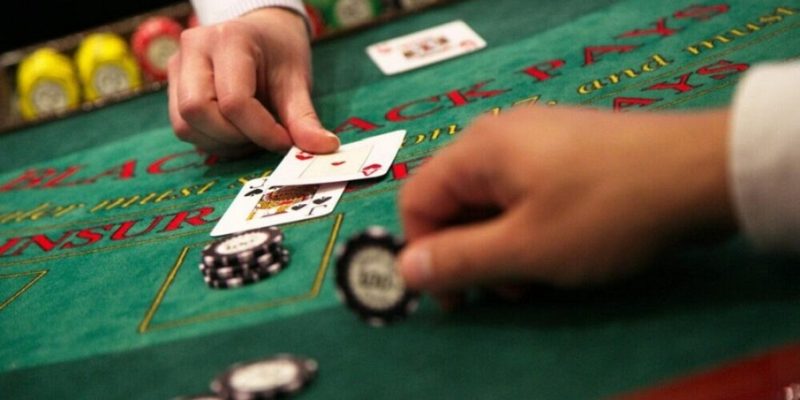
Card counting in blackjack, where specific deck compositions shift the advantage toward the player by 0.5 to 1.5 percent.
-
Video poker variations paired with aggressive player-club cashback and promotional point multipliers.
-
Skill-based poker rooms where superior decision-making yields a consistent win rate against weaker opponents.
-
Retail sports betting when a player identifies pricing discrepancies against opening lines.
For the casual player who visits a casino primarily for entertainment, understanding Kelly is not about finding an edge where none exists; it is about learning how professional math evaluates risk, bankroll preservation, and table limits.
Decoding the Formula Without an Advanced Degree
The mathematical representation of the Kelly Criterion for even-money or fixed-odds propositions appears intimidating on paper, but it breaks down into accessible arithmetic:
$$f^* = \frac{bp – q}{b}$$
Each variable represents a specific component of the wager:
-
$f^*$ (Kelly Fraction): The percentage of your total dedicated bankroll you should wager on the current hand or spin.
-
$b$ (Net Odds): The payout ratio received on the bet relative to your stake. For an even-money bet paying 1-to-1, $b$ is equal to 1. For a single-number roulette hit paying 35-to-1, $b$ is 35.
-
$p$ (Probability of Winning): The actual mathematical likelihood that your bet wins, expressed as a decimal.
-
$q$ (Probability of Losing): The probability that the wager fails, calculated simply as $1 – p$.
To see the formula in action, imagine a hypothetical coin-toss proposition. A generous host offers you an unfair coin that lands on heads 52 percent of the time ($p = 0.52$), meaning tails appears 48 percent of the time ($q = 0.48$). If you wager on heads, the host pays you even money ($b = 1$).
Plugging those values into the formula yields:
$$f^* = \frac{(1 \times 0.52) – 0.48}{1} = 0.52 – 0.48 = 0.04$$
The Kelly Criterion instructs you to wager exactly four percent of your bankroll on that flip. If your starting bankroll is $1,000, your first wager is $40. If you win and your bankroll swells to $1,040, your next wager becomes four percent of that new balance, or $41.60. If you lose and drop to $960, your next wager drops to $38.40.
The numerator in that equation ($bp – q$) represents your net statistical edge. If your edge is zero or negative, the result is zero or less, telling you that wagering any percentage of your bankroll is mathematically irrational from an investment perspective.
Why Full Kelly Is Far Too Volatile for Human Nerves
While the Kelly Criterion is mathematically optimal for maximizing long-term bankroll growth, using it at full strength—known as Full Kelly—is psychologically brutal.
The math behind Kelly aims purely at compounding efficiency across an infinite timeline; it has zero regard for human emotional comfort or short-term variance. In practice, betting full Kelly exposes a player to staggering swings in capital. In historical simulations of games with modest player edges, a full-Kelly bettor has roughly a one-in-three chance of seeing their bankroll cut in half before it doubles. Watching half of your hard-earned gambling funds evaporate during a normal statistical downswing causes most human beings to panic, abandon their strategy, or bet erratically.
Furthermore, the formula assumes that your estimation of $p$ (your win probability) is completely accurate. If you overestimate your edge by even a fraction of a percent, a full-Kelly stake becomes an over-bet, rapidly elevating your actual risk of ruin.
The Power of Fractional Kelly
To combat this volatility, experienced bettors rarely wager full Kelly stakes. Instead, they rely on Fractional Kelly, typically scaling their wagers down to half-Kelly ($f^* / 2$) or quarter-Kelly ($f^* / 4$).
Adopting a half-Kelly approach means you take the percentage generated by the formula and cut it in half. In our coin-flip example, rather than betting four percent of your bankroll, you wager two percent.
This modest adjustment delivers profound structural advantages:
-
It captures roughly seventy-five percent of the theoretical maximum growth rate of full Kelly.
-
It slashes portfolio volatility and drawdown depth by fifty percent.
-
It provides a wide safety cushion against minor errors in edge estimation.
-
It dramatically softens the emotional anxiety caused by cold runs.
For anyone managing money in volatile environments, fractional sizing transforms an aggressive mathematical exercise into a sustainable risk management protocol.
Practical Lessons for the Casual Casino Visitor
Even if you never learn to count cards or exploit promotional loopholes, internalizing the principles behind the Kelly Criterion provides powerful lessons that can preserve your entertainment budget.
Your Bet Must Scale to Your Bankroll, Not Your Ego
The single greatest mistake recreational casino players make is setting their unit bet size based on table minimums rather than their personal capital. Sitting down at a $25 minimum blackjack table with a $200 total trip bankroll means you are wagering 12.5 percent of your entire stake on a single hand. Even if you were playing with an edge—which, under standard rules, you are not—wagering twelve percent of your bankroll represents reckless over-betting that guarantees a swift exit during normal distribution runs.
If you want your entertainment bankroll to survive an evening of standard table variance, your individual wager size should represent a tiny fraction of your bankroll, typically between one and two percent.
Progression Systems Are Mathematically Defective
Many casual gamblers believe that progression betting systems—such as doubling your bet after every loss in the Martingale system—can overcome negative expectation. The Kelly Criterion illuminates why this is dangerous.
Progression systems instruct players to dramatically increase their bet sizes precisely when their bankrolls are shrinking. Kelly proves the exact opposite: when your capital declines, your wagers should contract to preserve remaining equity. Progressive recovery systems do not alter the underlying odds of the game; they merely package frequent small wins alongside rare, catastrophic wipeouts that eliminate an entire bankroll in a single bad shoe.
Bankroll Definition Dictates Risk
In the Kelly framework, your bankroll is defined strictly as the capital specifically set aside and fully unencumbered for that activity. It is never your savings account, your mortgage payment, or your next paycheck. For a casual player, treating an entertainment bankroll as a discrete, self-contained fund ensures that whatever variance takes place at the tables has zero structural impact on everyday domestic life.
The Kelly Criterion was never intended to be an entertaining casino trick; it is an unyielding mathematical mirror. It demonstrates that long-term survival in probabilistic environments depends entirely on matching the size of your commitment to the strength of your verifiable edge. In a world where the house almost always holds the upper hand, recognizing when the math tells you to keep your chips in your pocket is the most valuable discipline you can cultivate.
What is your reaction?
Excited
0
Happy
0
In Love
0
Not Sure
0
Silly
0